
[WEEK #37/52]: “If you need to make 100 mistakes before becoming successful, then wouldn’t you be happy after each mistake you made?”
[Topic] Sharing my Worst-of-All-Time investment mistakes, and recent hiccups, so you don’t make the same ones.
My Worst Investment Loss Happened Last Year from ETH, Never Again.
Today’s newsletter is inspired by the quote I heard on Compound & Friends Podcast with Josh Brown and Michael Batnick:
This famous Wall Street mantra has been molded over the years to imply that a “great investor” is someone who makes a massive, catastrophic mistake early in their career, learns a brutal lesson about risk, and never lets it happen again. If they lose a fortune a second time, they aren’t a great investor.. they are just reckless.
It implies every great investor made a catastrophic mistake, but ensured it did not happen twice.
While my catastrophic mistake wasn’t un-profitable in 2025, it was losing 95% of my annual profits from Etherium in late 2025. Went up 400% on the year in 3 months, and then right back down to only being up 20%. Was still a nice return, but an awful experience I will never do again. I still think about that daily, it’s my chip.
Not Losing This Fund.
So when I first launched this new fund, Thoughtful Directions Capital, I was openly very worried that I was doing the wrong things by having a ‘traders’ mindset. I kept wanting to be a value investor, but I just couldn’t stop trading. I was scared from ETH, and I was running scared every time a stock even sneezed. I covered my Investor 1 vs Investor 2 dilemma back in Week 22.

Well it’s now week 39 or something like that, less than 20 left!!, and I’m happy to say that ever since July 7th I totally broke that Jekyll Ξ Hyde trading mindset. I broke that on July 7th (story for a later time), but from that date I just completely removed the feeling of FOMO from my emotional state when investing in stocks. It’s not come back, and I don’t really know why it would. It’s useless. I optimize only for FOME (fear of moving early). Implying that if I’m not the innovator moving first, I’m probably the unknowing idiot moving last. So I should not fear being first, I should hunt for out of favor, and I should lean in when I’m going solo.
Almost the same hour we approached our new high-water mark, I mis-judged Lulu
New strat is working INCREDIBLE.. but as I learned I’m still human. Capable of not thinking with common sense, as LULU’s been falling apart for years.
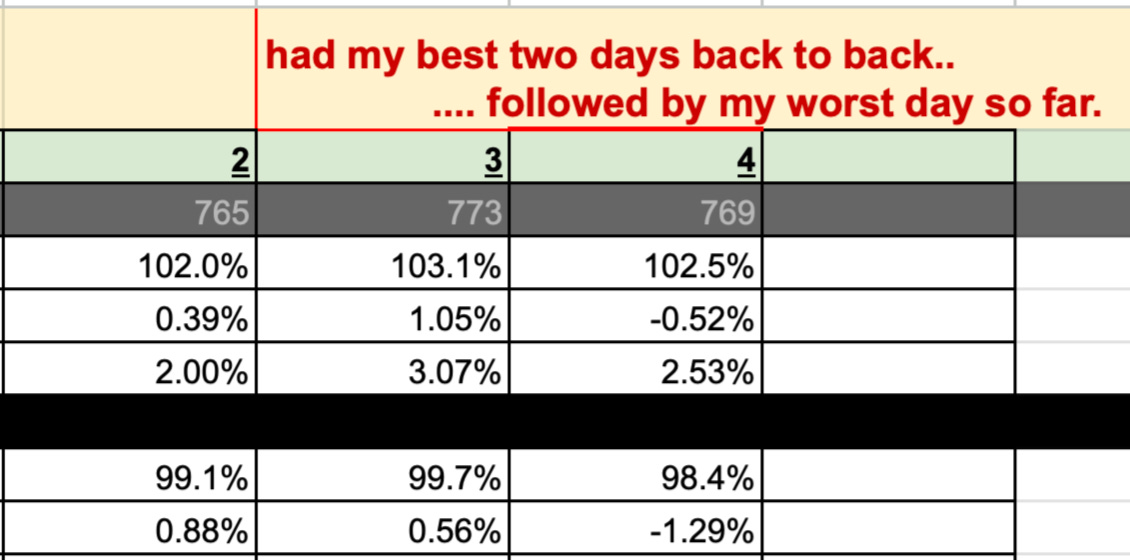
As of Thursday (Sept 3rd) I had gotten our fund back to break even. But as I’m writing this on Friday (Sept 4th), gosh, I write this from a place of disappointment as we gave 1% of it back (our worst day ever, and it wasn’t from dumb trading mistakes, it was from incorrect underwriting of a deal I should have known better than to value at a 15x on FAIR pricing targets).
I cannot describe how hard I worked or how proud I was of hitting that break-even milestone. We were consistently beating the $SPY over the course of August, and I was making back all our losses while maintaining 65% cash, and taking minimal risk. It really was beautiful. I touched what it felt like to be a true value investor.
I did it through a very simple method = Investing only based on things being a bargain price, after careful underwriting.
The system fundamentally relies on only two decisions:
#1 always opting for conservative estimates in all scenarios
and #2 never buying above ‘fair’ pricing.
When I stick to that discipline, despite how many I miss on the upside, we make money. It’s the key to waiting for your pitch.
I had not made a ‘buying’ mistake in 4-6 weeks.
Meaning, just about everything I had bought over the last month was helping the portfolio go up regardless of bull/bear macro market. And, it was correctly sized and priced within my very stern policy.
It was a thing of beauty to witness. The market was down, we were down less. The market was up, we were close enough to it on either side of it that it was a great day. Then the market would go down, we’d barely move down, or maybe even stay even. We did that every day for ~4 weeks.
On the exact day, nay, the exact hour that our fund got back to break even (I worked so so hard for this) was the same hour that LULU 0.00%↑ Lemon’s earnings call approached. If you can sense the tone shift, this is where I made a mistake.
New CEO to Save the Day?
I was (and still am) excited by the incoming CEO. She’s proven nothing yet as the LULU leader, but here’s a few things that had me excited.
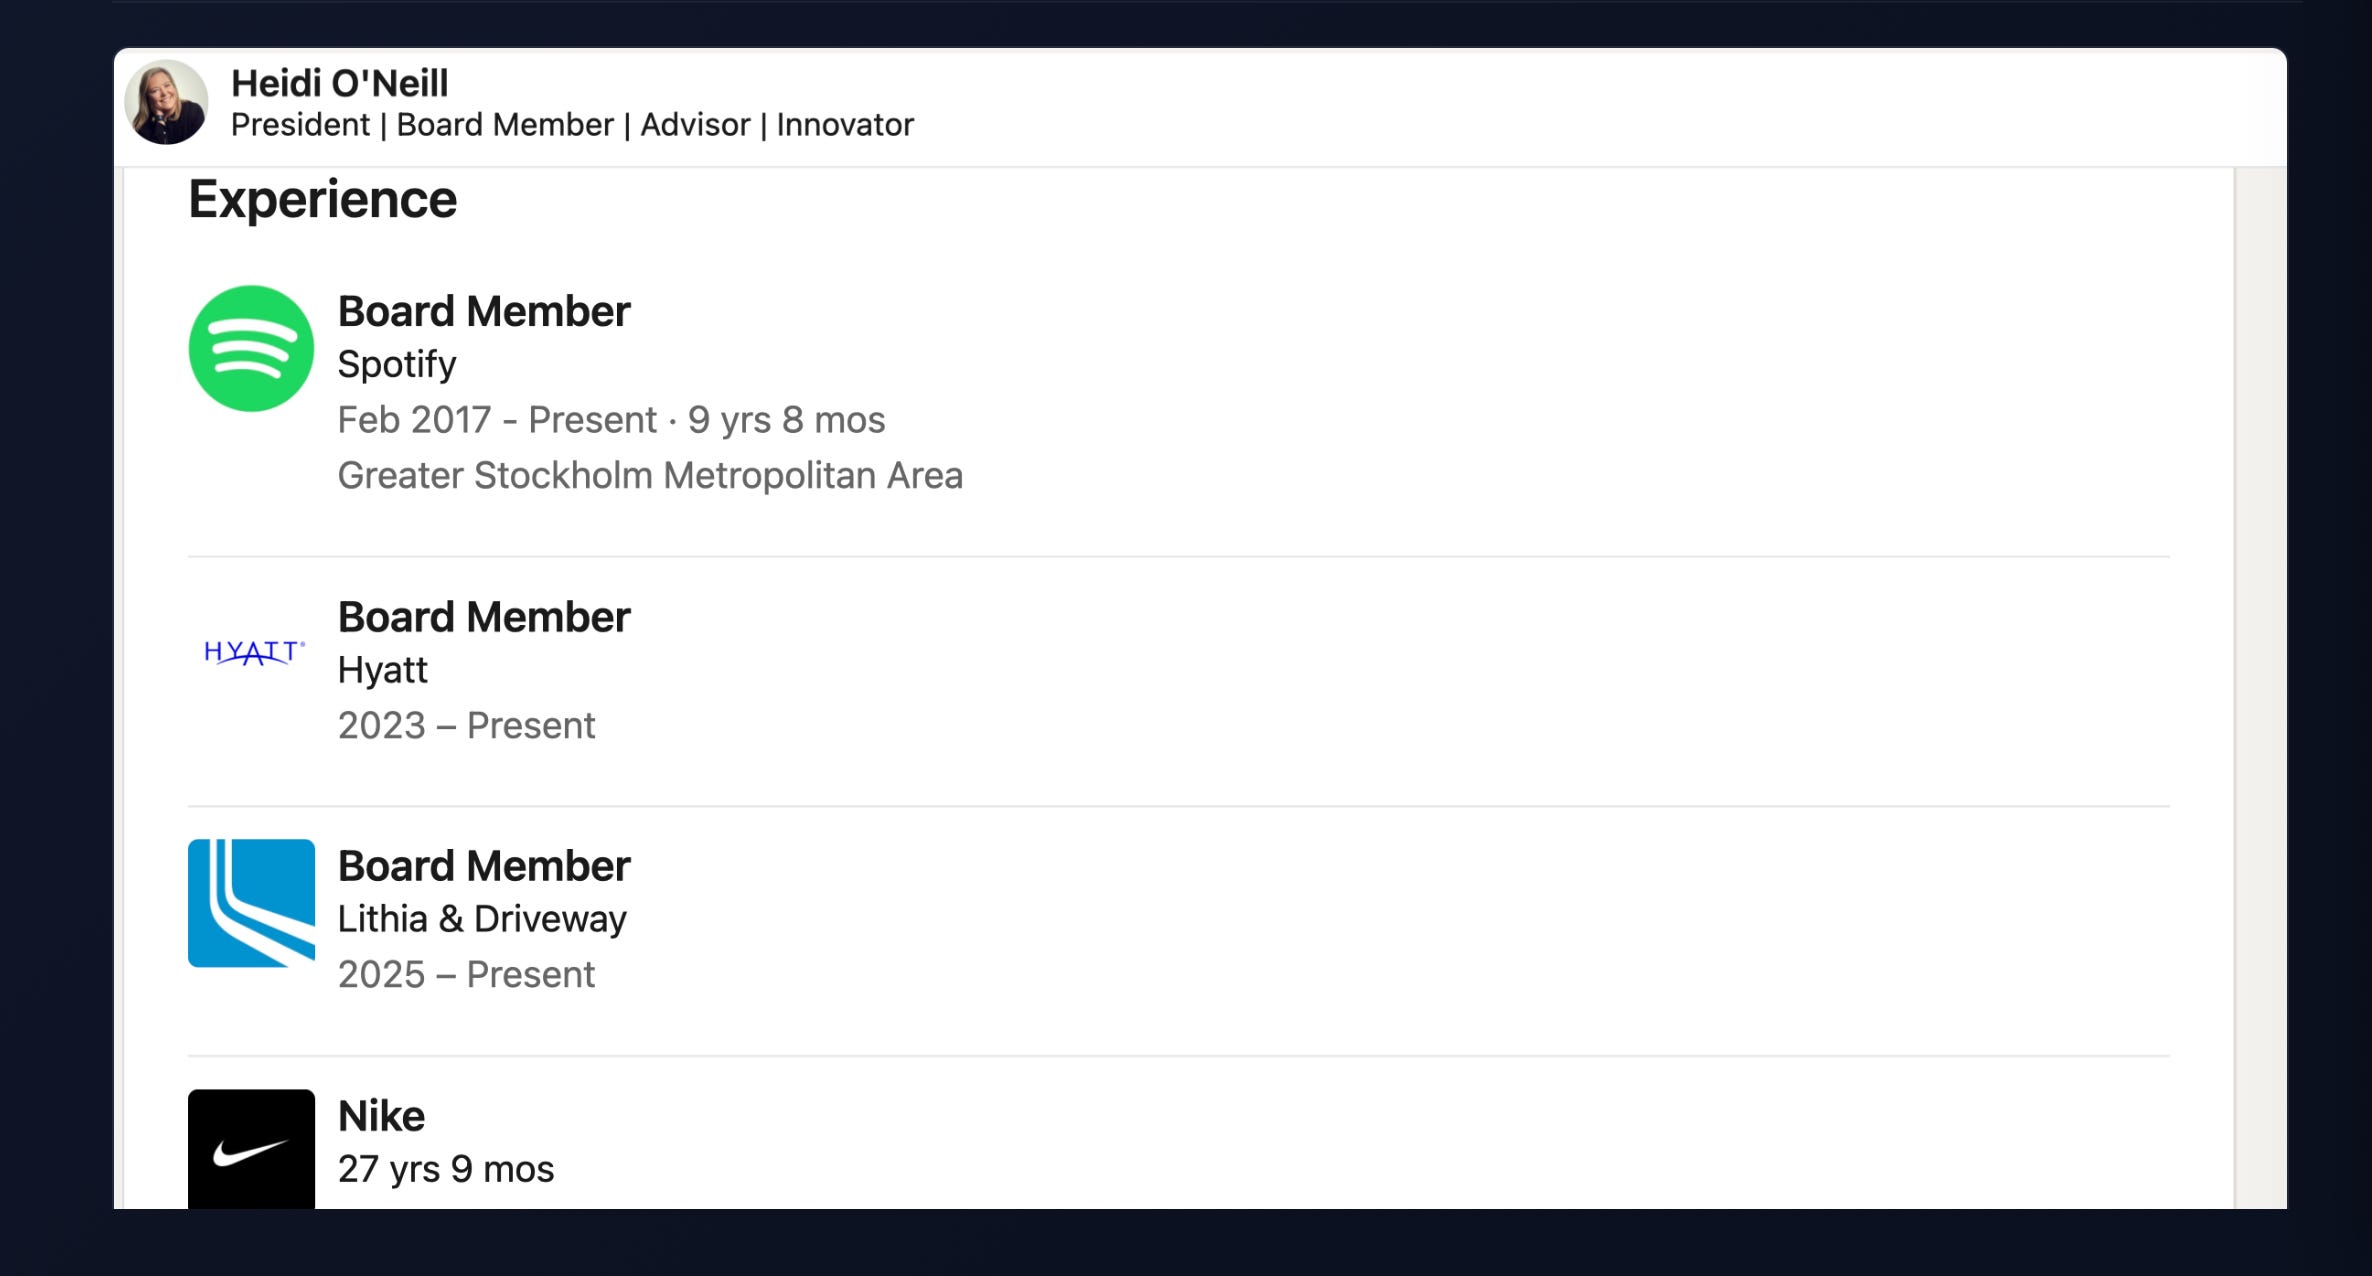
#1 She is on the board of three public companies, one of them being Spotify! SPOT 0.00%↑. She’s been on Daniel’s board for nearly a decade.
#2 She helped launch Nike Women’s from nothing in the 1980’s (?) to a billion dollar brand.
#3 Three executives already left this week, the week before she starts. That tells me that she is cleaning up house even before she gets there. And nobody was hired in their place, so she’s going to get in there and hopefully hire some bad ass mojo’s.
But as Ben pointed out to me, he fell for this with Nike.. so watch out.
Current Co-CEO’s Did Their Best, but Not Good Results
The current CEO situation is a mess. The business has been sliding for years, and the most recent effort only made things worse.
They brought in two people from LULU management to be CO-CEO’s.
Let’s start with that issue… if you have two CEO’s… then you have none.
But giving them the benefit of the doubt, I listened to multiple earnings calls.
Absolutely brutal.
Constantly blaming things they don’t control for their lack of performance.
Constantly dropping revenue goals.
Their inconsistency of launches for new successful products seemed to always get blamed on ‘negative social media sentiment’ or ‘bad economy’ or ‘competition.’
Well if it is a bad economy.. then how come your competition are selling so much more?
Their excuses made no sense, and it was clear this was nothing more than a polished up pony show as we await a real CEO to lead.
I figured that the two interim CEO’s would be bad, but not do too much damage. I was sadly wrong.
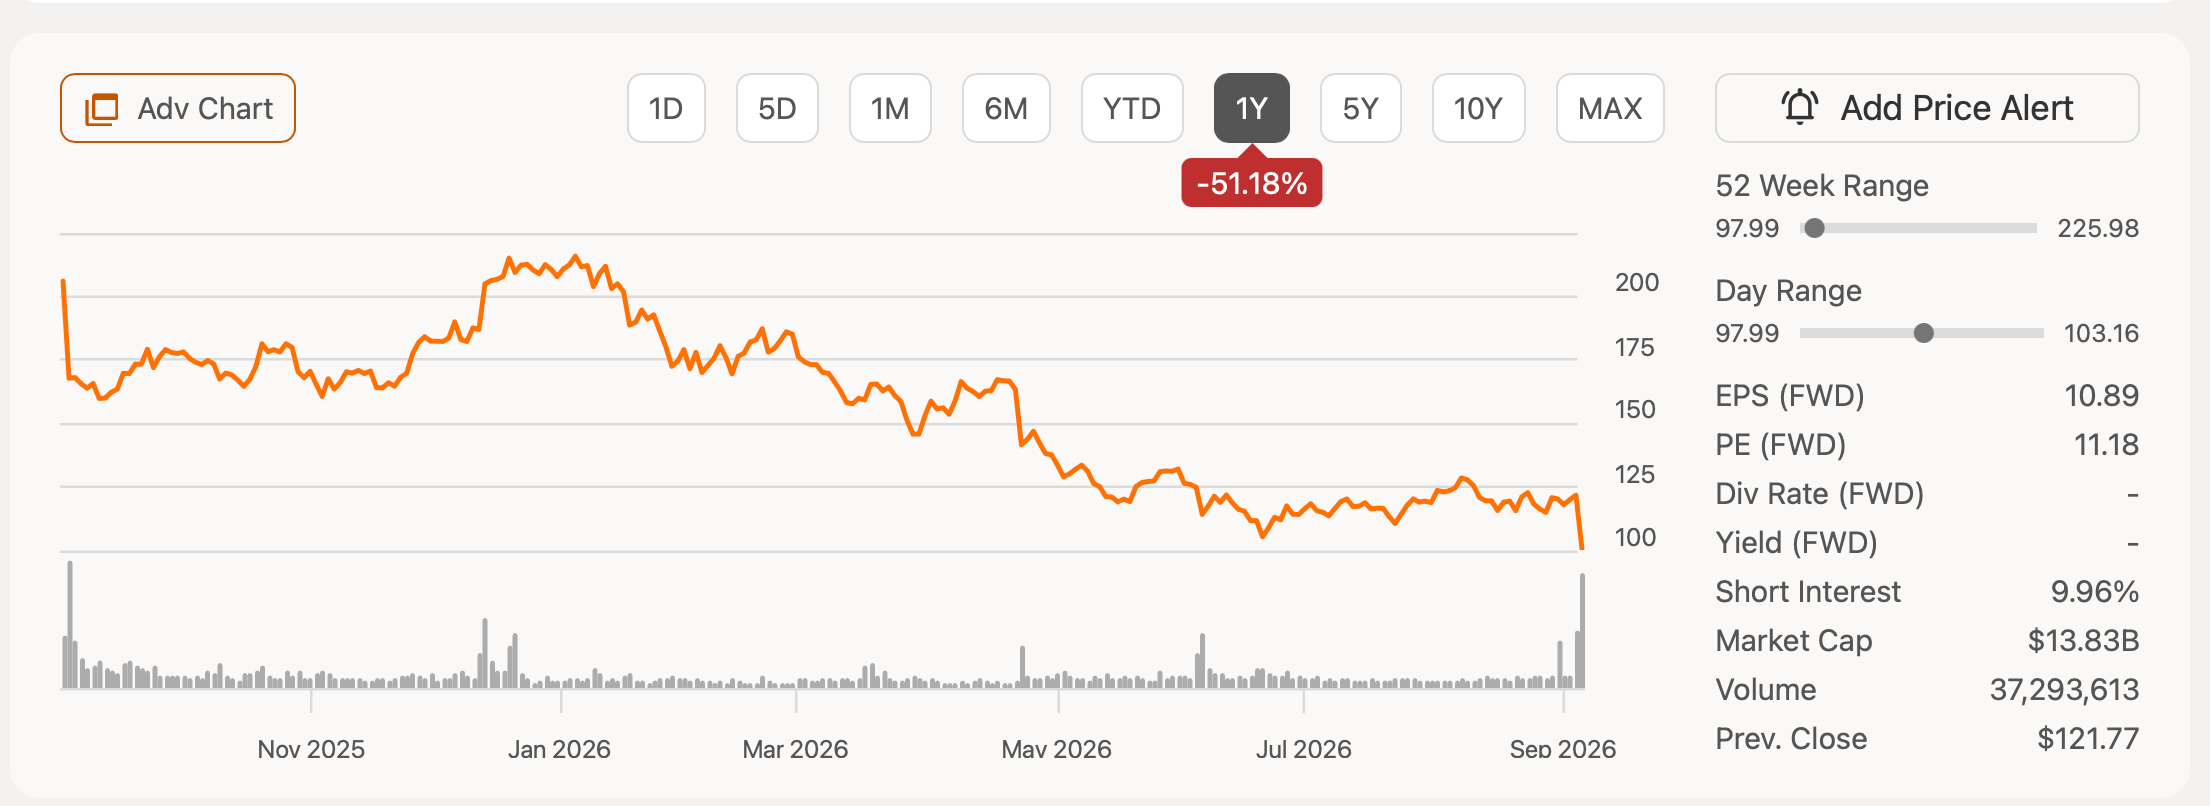
The stock price, and the revenue, and margins, all paid the price of poor leadership. By the way, I’m not the only one who thinks this.
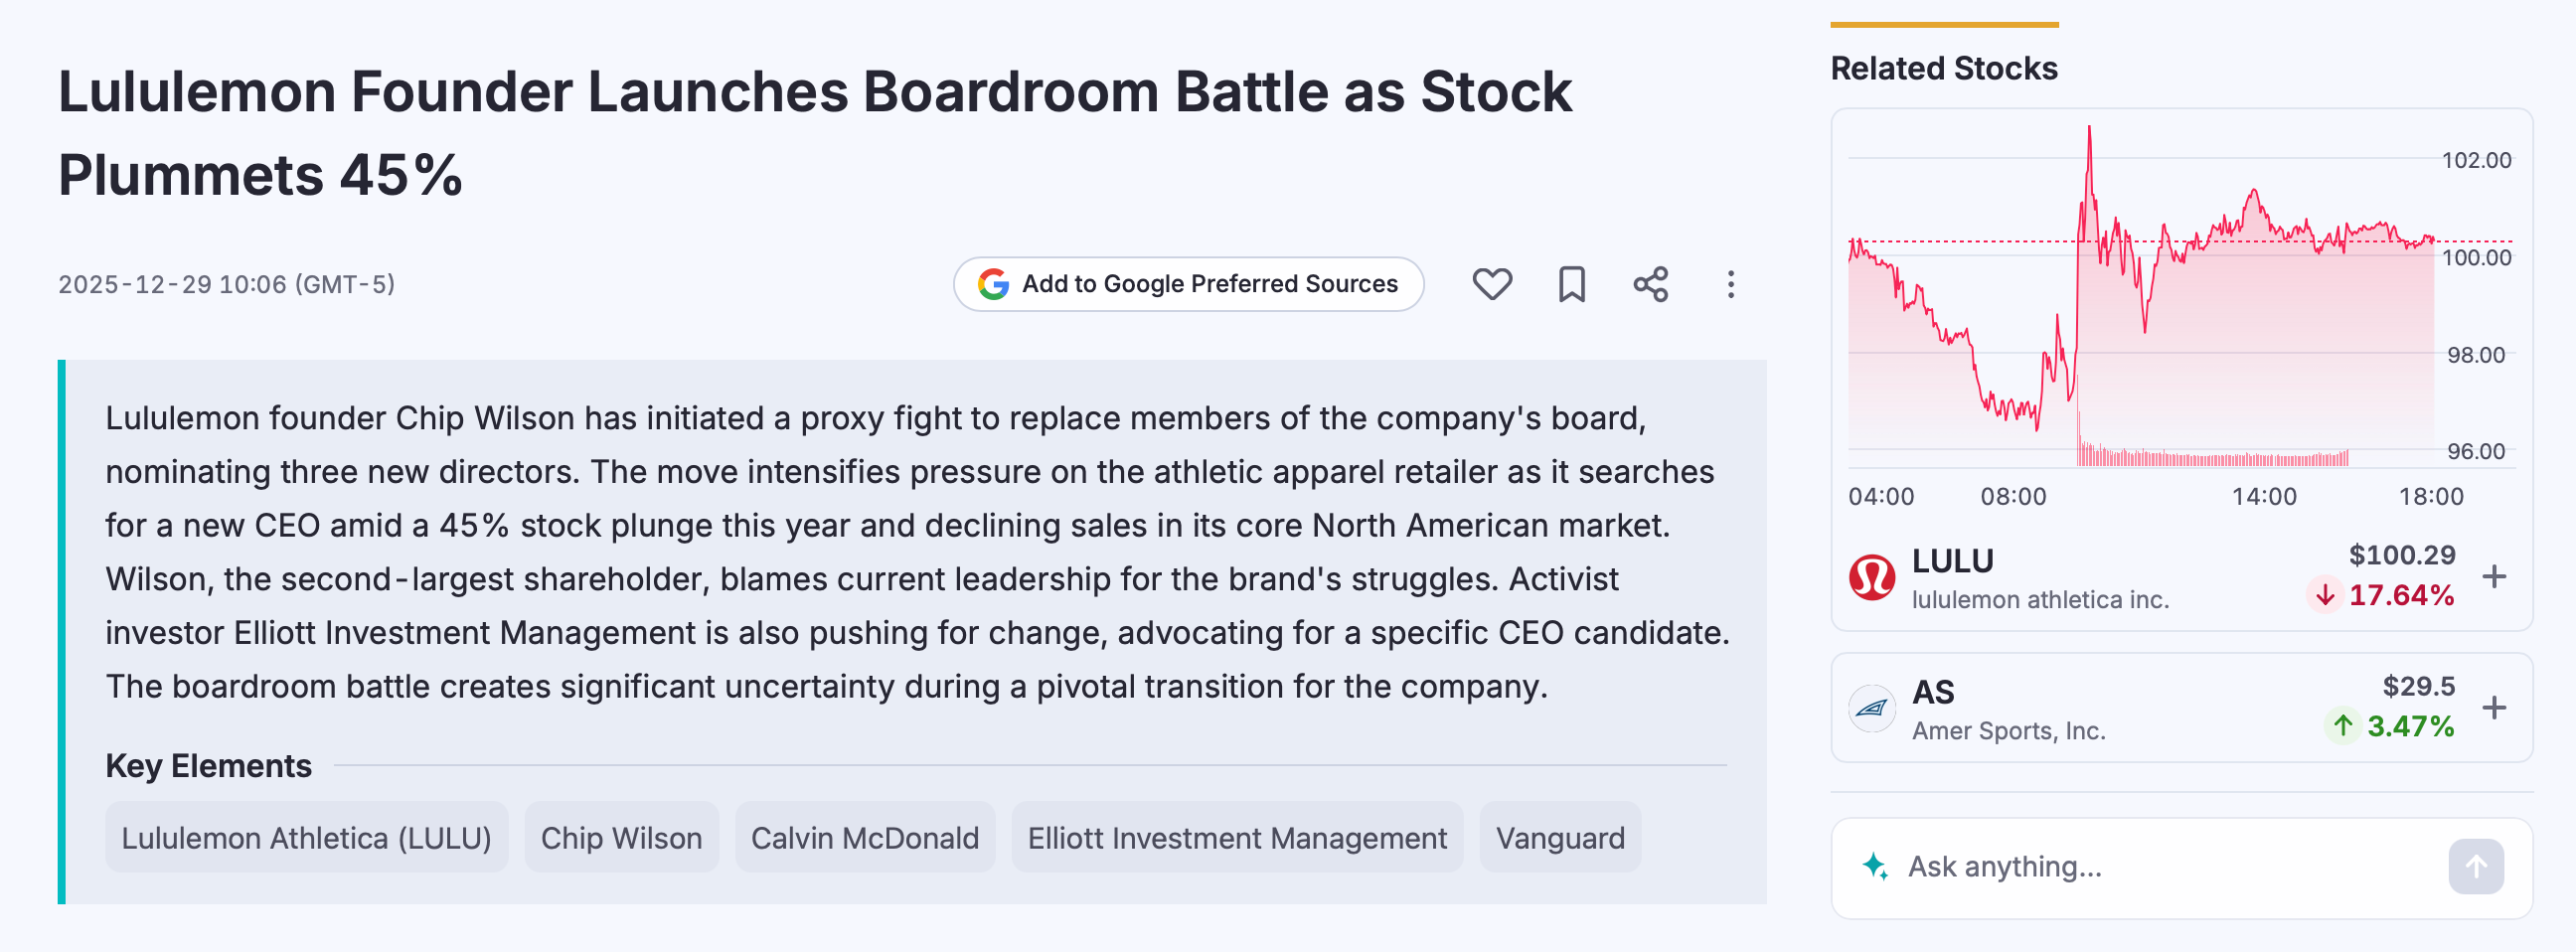
It’s painful to see the numbers, because as of last week LULU reported a decline of 10% in USA revenue. That’s down from positive 12 months ago, and the Street expected -4%.
So, they really underperformed. That gives very little confidence going into the future quarter.
But…. and it’s an important but! Our CEO SAVIOR starts Sep 8th!!
And this is where I made the mistake.
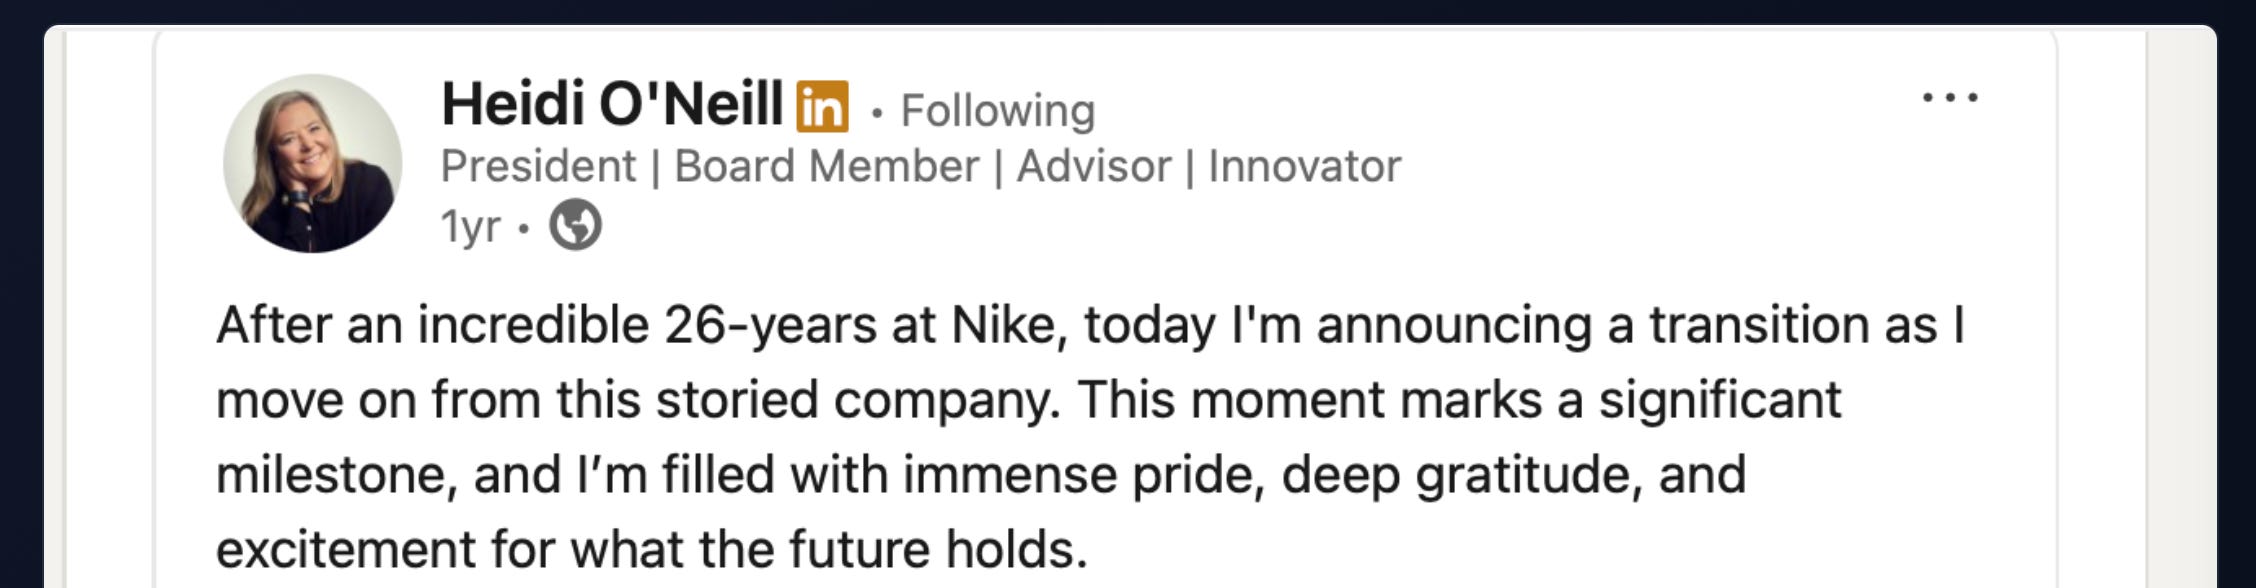
I categorized LULU as ‘15x = Fair’ when new CEO was not even starting until that following week
The key question I had to answer, which was subjective, about LULU 0.00%↑ underwriting…. is a FAIR price 10x for this, or 15x for this?
Normally, I have absolutely no issue answering this. I opt to 10x’ing owner earnings unless it’s a truly exceptional business.
It was very clear LULU has about $1.2-1.35B of annual earnings power, and +/- $0 of liquidatable assets over liabilities, so the simple question I asked myself, is this company’s cashflows worth $12B or $18B?
If it’s $18B (that’s 15x), then LULU 0.00%↑ was a screaming deal trading at $120/share. And I should have ~$75K into it.
If it’s fair price is $12B (that’s 10x), then I should absolutely not have anything invested, and I should be waiting for my clearing price to enter of $101-109, and only enter with $25K.
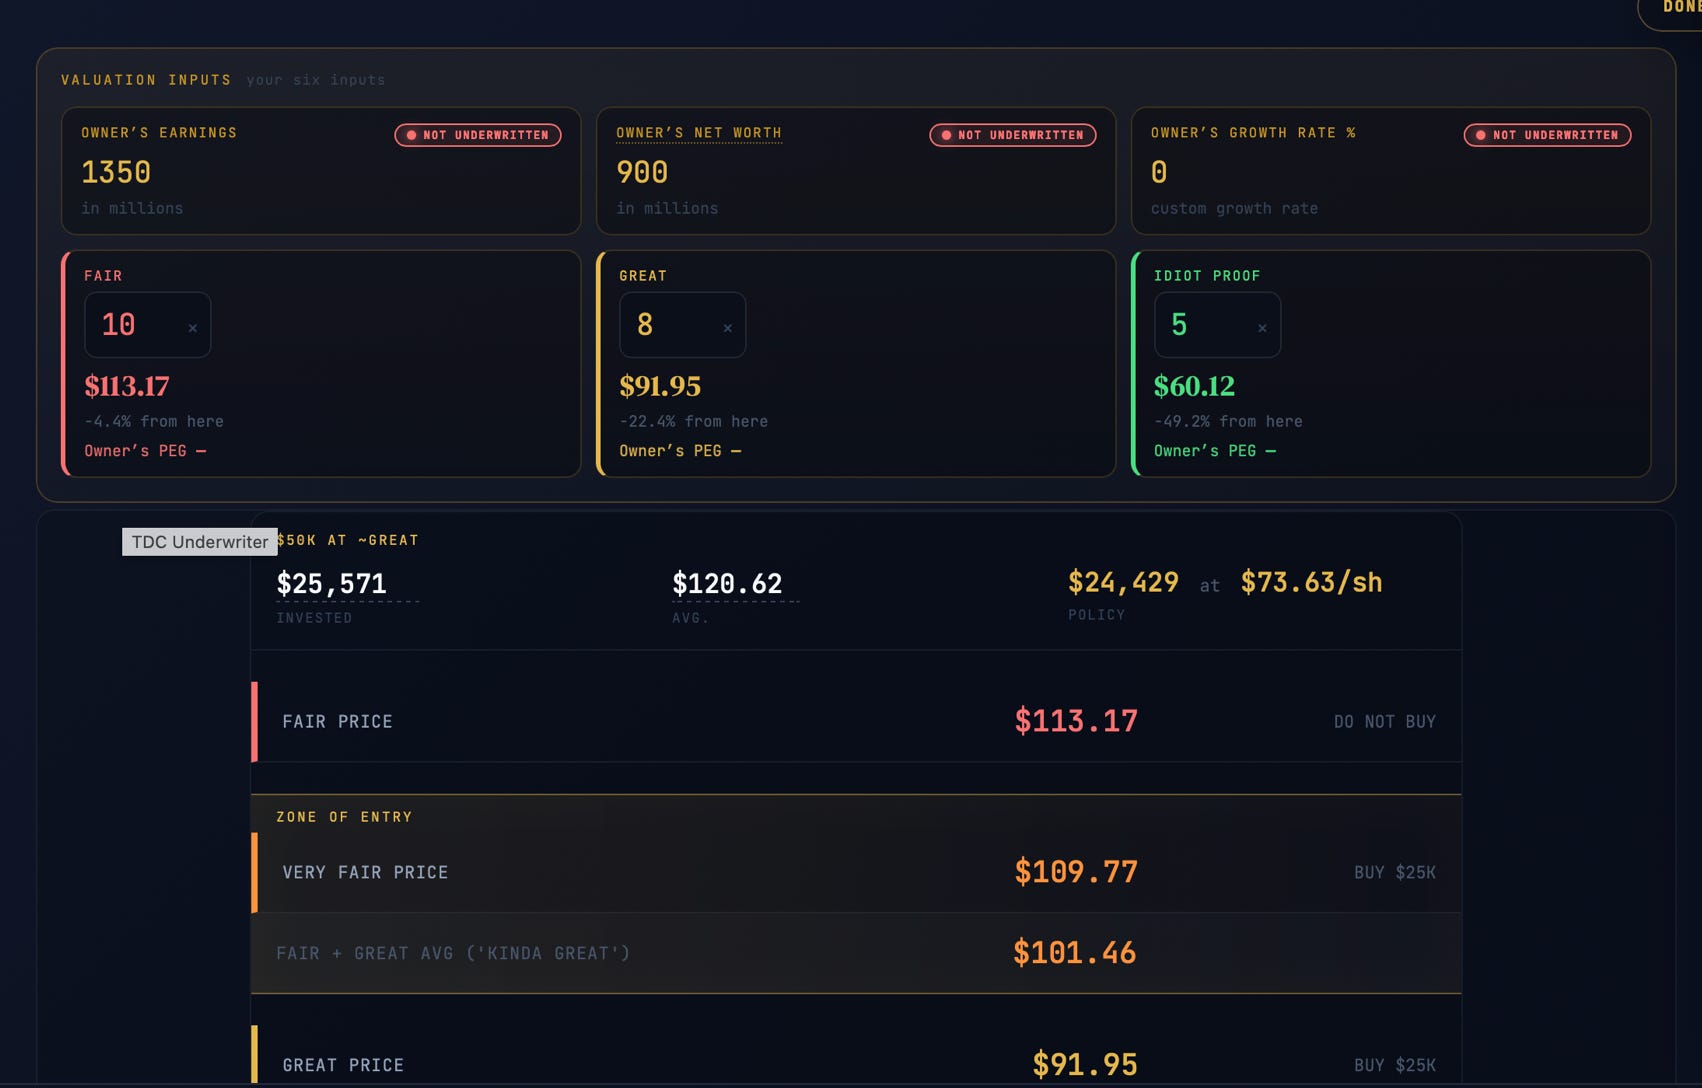
I made the call just before the earnings call kicked off that I felt this was a 15x. Which was the wrong call, because all bits of common sense tells you this is a 10x’er. However, I over-indexed on Heidi being CEO, thinking her clout on Spotify’s Board, Nike leadership, and removing of prior mgmt was enough of a signal to the market that LULU 0.00%↑ is turning over a new leaf.
I 100% knew that current management was awful, I knew the quarter was going to be brutal, you could see it in the numbers, and their guidance last Q was negative.
But I discounted the risk of what two part-time co-ceo’s with no prior experience running a company during turbulent Tariff times could handle.. And, I added too much premium to the risk that Heidi was coming in as CEO next week.
It sounded great - but reframing it, she didn’t even start for another week!I
WHAT WAS I THINKING GIVING THIS 15X AT FAIR VALUE..
That’s a brutal set up to get this wrong in my system, because it is straying from my two fundamentals I covered at the start of this writing today:
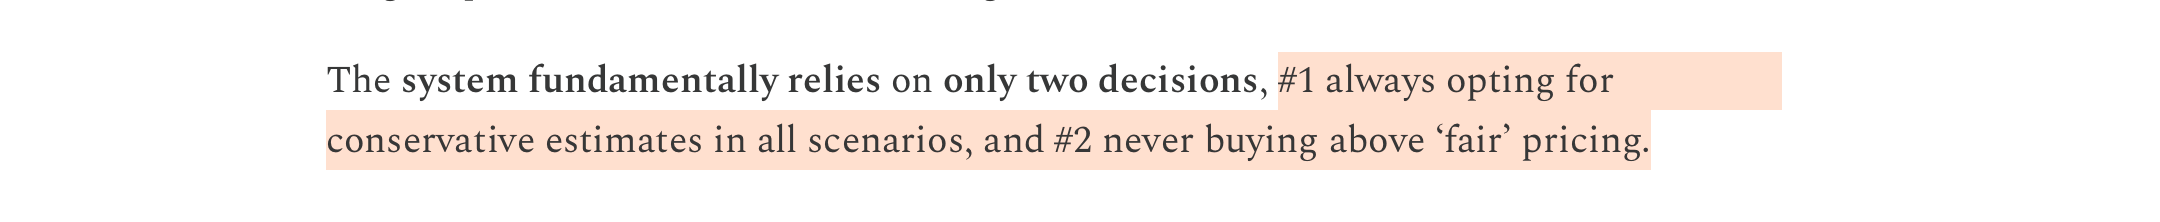
I broke rule #1 by giving benefit-of-the-doubt. I should NOT be paying for hope, a great investor only pays for proof. By breaking rule #1, I then caused myself to over-extend and break rule #2 since the goal posts for ‘fair’ were on the wrong side of the field.
Upset with myself.
My internal voice was also screaming at me prior to all this, you can see from my text this was by biggest flagged worry, but I talked myself out of it being a risk because ‘whatever, the NEW CEO will save us! She deserves a valuation premiums today!’
So silly. I should have waited.
I watched 100’s of pitches fly by, and only swung at a select few this past 6 weeks.
It was a completely new investment style, and it changed my returns significantly.
So losing a good portion of the last 2-3 weeks of returns from a mis-categorization of LULU being a higher quality stock than they rightfully deserve, is brutal for me.
As is how it goes…
So without dwelling.. the only question now is, what do we do so that we make money?
The first step, is to codify the rule, print it out, and hang it above my desk.
1 major mistake = 1 major rule. Never to be broken again.
We’re up to 7 or 8 hanging, and the good news is that once they are up there, they do not seem to repeat with any sort of consistency.
This rule involved me putting in a framework for how I select between FAIR being 10 15 or 20x.
More to come in the later Monthly edition of our full portfolio underwriting at end of Sept.
I love to think about all sorts of things. Finance, and also life/education.
Request Your Investor Invite:
Dear Founders, Investors, and HNWs,
If you’re running a startup, working for corporate, or lucky enough to have a pile of cash, in all scenarios it’s important to compound your wealth.
Stocks are not for everyone, especially individual stock picking.
It’s a skill that requires years of hard lessons, and losing money.
A handful of investors stick through the lows, and realize how lucrative it can be.
So each month, we’re going to pick ONE STOCK and do a deep diver conversation with a hand-selected group of business leaders.
You can find out more details by clicking the above image or link.
Next Monday:
We’re covering either music, or these below Qs as my ‘dedicated’ podcasts hosts delayed our recording today :)
Q1: What’s the key to raising a family?
Q2: How would you fix the USA education system?
substack.meetdonstein.com
~Don
https://x.com/donversationz
substack.meetdonstein.com